
The midterm election message is loud and clear. The political winds have shifted. What does that mean to your taxes? The days of tax cuts are over. Taxes will likely go up. Question: What should you do about it? Answer: Engage in tax planning now, before it’s too late.
At The Blum Firm, we routinely save clients millions of dollars of taxes. We have a number of tools in our toolbox. One of our favorite tax-saving tools is an estate freeze. In a nutshell, here’s how it works. You sell appreciating assets to a trust for your family. The trust gives you back a note. The trust pays you back over time. The note is still in your estate, but it’s frozen in size. The assets grow in a trust that is out of your estate.
I’ll elaborate with an example. Say you have $10 million of investments (marketable securities, real estate, private equity deals, etc.) Step One: Create a Family Limited Partnership (“FLP”) and contribute the investments to the FLP. Step Two: Create a trust (it can be a Defective Grantor Trust (“DGT”) for your kids, a Spousal Lifetime Access Trust (“SLAT”) for your spouse, or a Beneficiary Defective Inheritors Trust (“BDIT” or 678 Trust) for the benefit of you and your family. Step Three: After a month or more, sell your FLP interests to the trust. Because the trust is a “Grantor Trust,” you pay no income tax on the sale. Step Four: Hire an appraiser to determine the value of your FLP interest. Because of discounts for lack of marketability and lack of control, the value is discounted to $6.5 million. Step Five: The trust gives you a note, and will pay you back $6.5 million over time (plus interest at the IRS approved rate). Results: The $6.5 million note is still in your estate, but the investments are now in a pocket that is out of your estate. If the investments grow from $10 million to $20 million, you have avoided paying a 40% estate tax on $13.5 million. That’s a savings of $5.4 million.
Moreover, because it’s a Grantor Trust, the income is taxed back to you on your income tax return, instead of being taxed to the trust. When you need money to pay the income tax, the trust sends you a payment on the note. The note gradually burns down to zero, and your estate tax goes down even more. Eventually, all the assets are owned by a trust that benefits your family, free from estate tax, and also protected from creditors. We call this technique “Squeeze, Freeze, & Burn.”
This is just one of many tools. There are other ways to save tax, both income tax and estate tax. The key is timing. The earlier you do it, the better. You want to capture as much growth as possible in the trust. But the other reason to do it sooner rather than later is because the law could change. The last time Congress tried to kill this technique was in 2021 when the Democrats had a narrow margin and needed every D Senator for it to pass. The bill fell two votes short. The Congress elected on Tuesday does not have a narrow D margin.
The 2021 legislative attempt was proposed by Senator Bernie Sanders and entitled “For the 99.8% Act.” Look for that legislation to re-emerge now. It would have shut down many of the tools in our toolbox. But here’s a critical point: the legislation grandfathered anyone who had engaged in that planning before the new law passed. The likelihood is that planning you do today will stick, even if the law changes later.
The Democrats have an expensive legislative agenda, especially when it comes to healthcare and “Medicare for All.” It will take a lot of money to pay for that agenda. Some could come from spending cuts, but the more likely scenario is tax increases.
As the photo of AOC attached to this post screams, there is a heavy sentiment to “Tax the Rich.” There is still a lot of resentment about the tax cuts in OBBBA (“One Big Beautiful Bill”) that passed last year without one Democrat vote. One of the provisions of OBBBA was to increase the estate exemption to $15 million. Don’t trust it to stay that high. Senator Chris Van Hollen has already introduced legislation to lower the exemption to $3.5 million for estates and $1million for gifts, and raise the tax rate from 40% to 45%. We may have a two-year window to “use it or lose it,” if Pres. Trump vetoes any tax increases. However, the way “horse trading” happens in Washington, we can’t count on that. There’s always the possibility of some “give and take” in order for Trump to get something else he wants.
My advice is to act now, while we still know for sure what the law is. Even if the law doesn’t change, the planning could still save your family millions of dollars. We’ve helped hundreds of clients with this type of planning, and they’ve reaped significant benefits by being proactive. And by the way, when we engage in this kind of planning, we are fully transparent with the IRS and disclose everything. Not once have we received any pushback from the IRS.
Marvin E. Blum
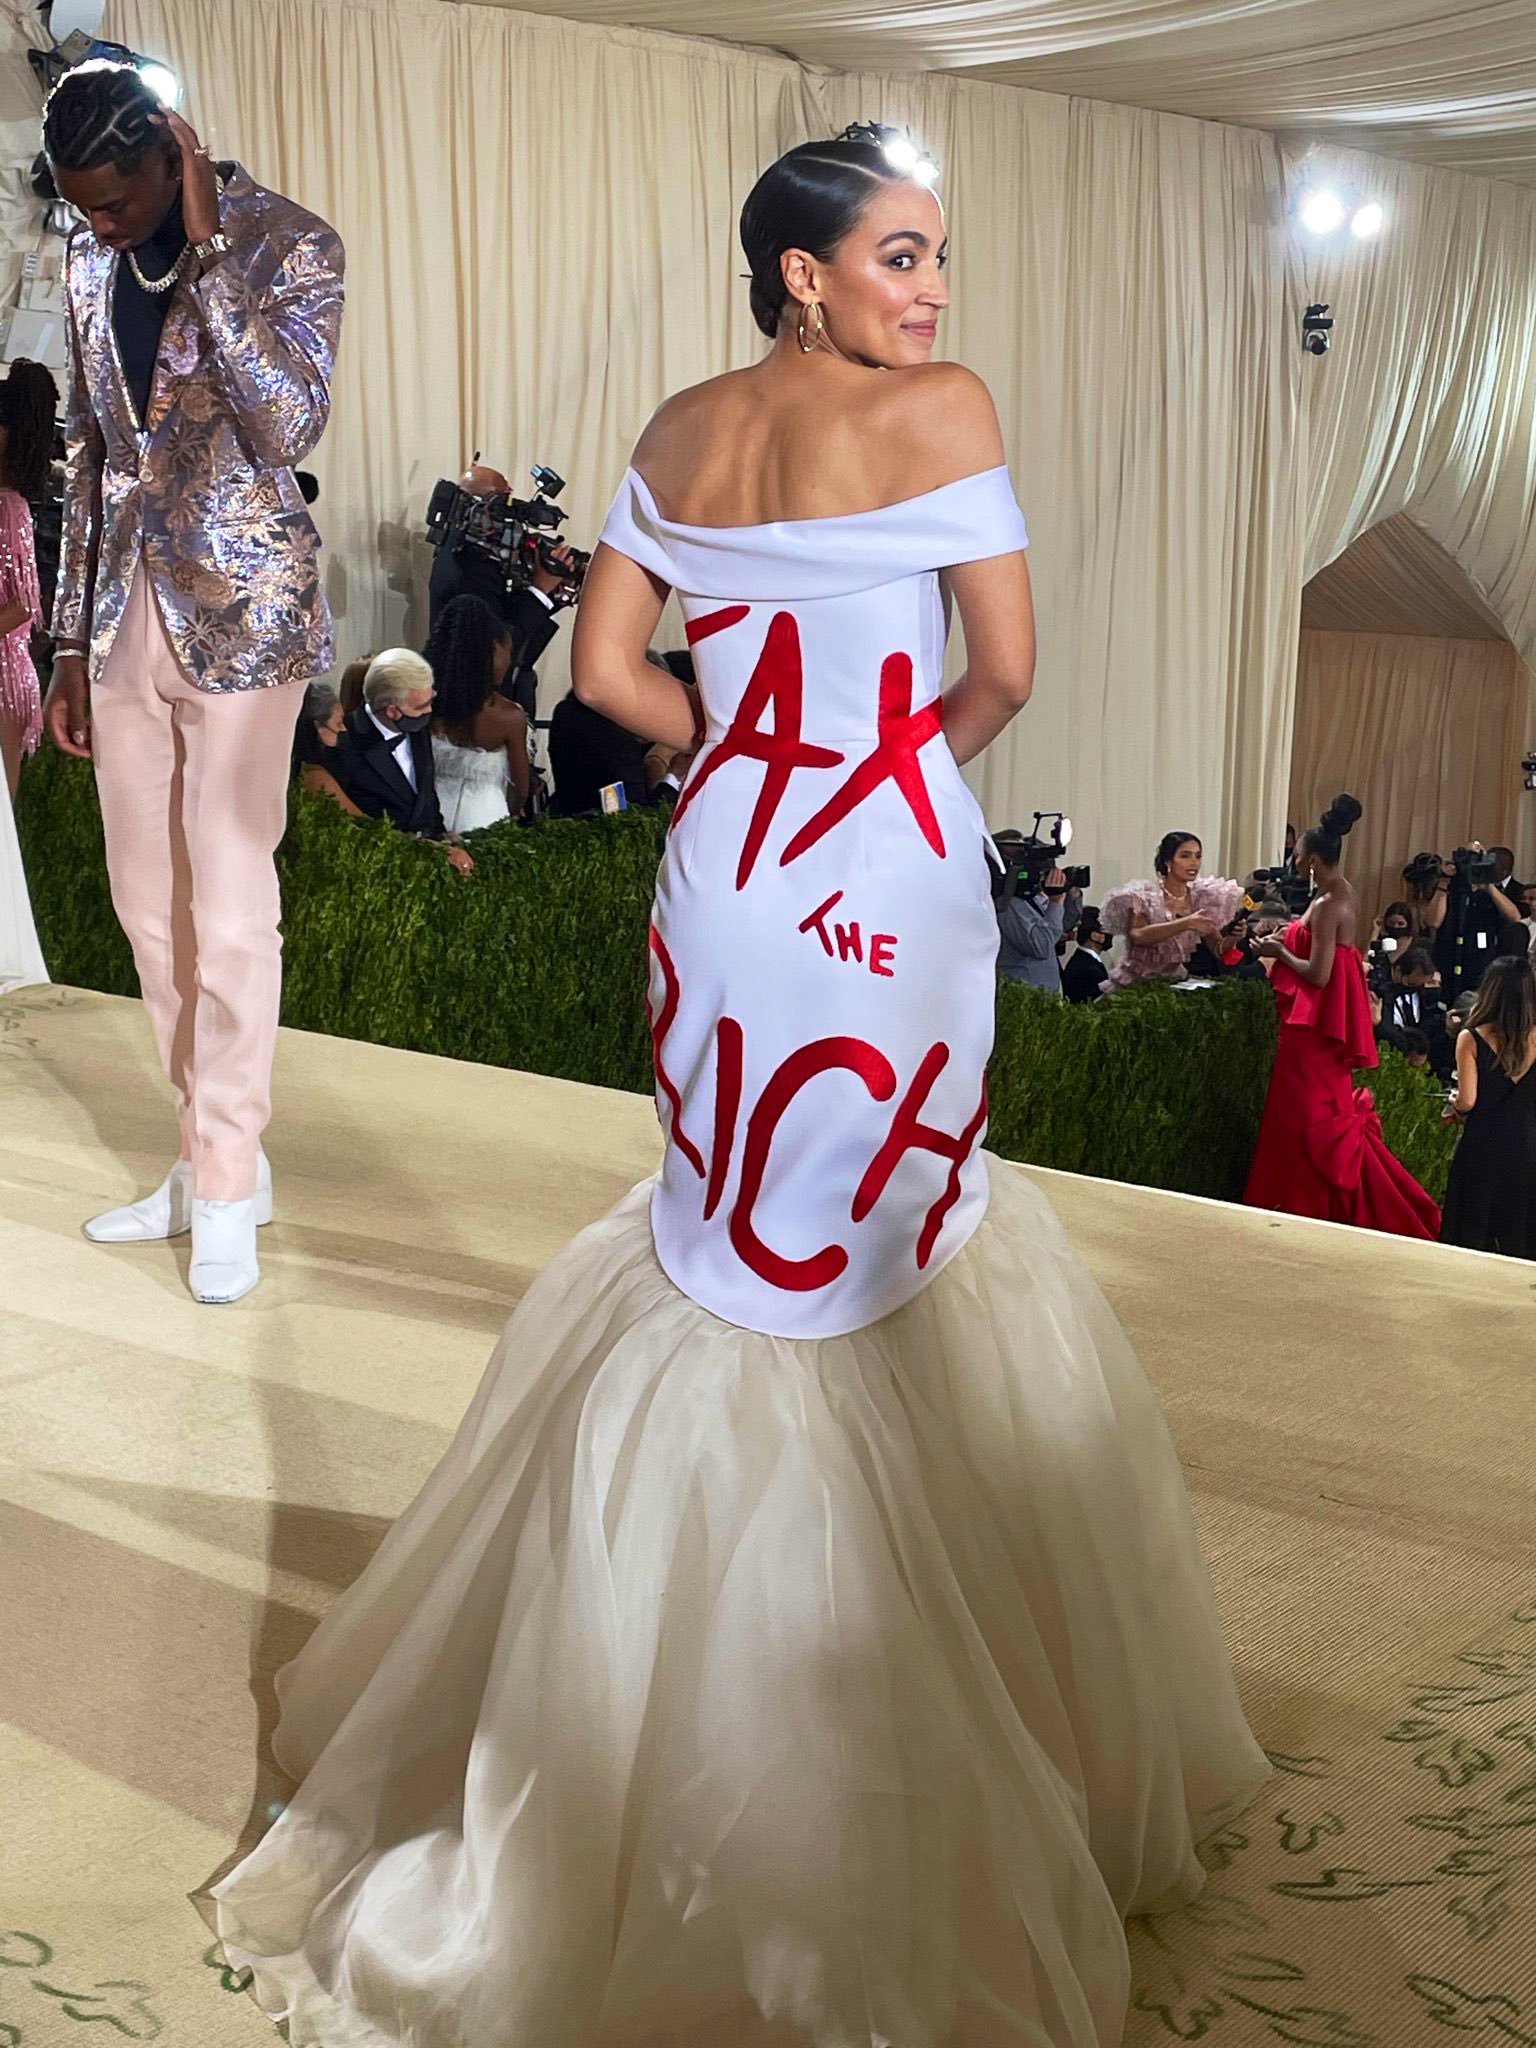
Rep. Alexandria Ocasio-Cortez’s 2021 Met Gala gown expresses public sentiment to “Tax the Rich.” Pay attention to the signs and act now to save taxes.